
Reviewed 19 September 2026 · General information, not individual tax advice.
Sales records
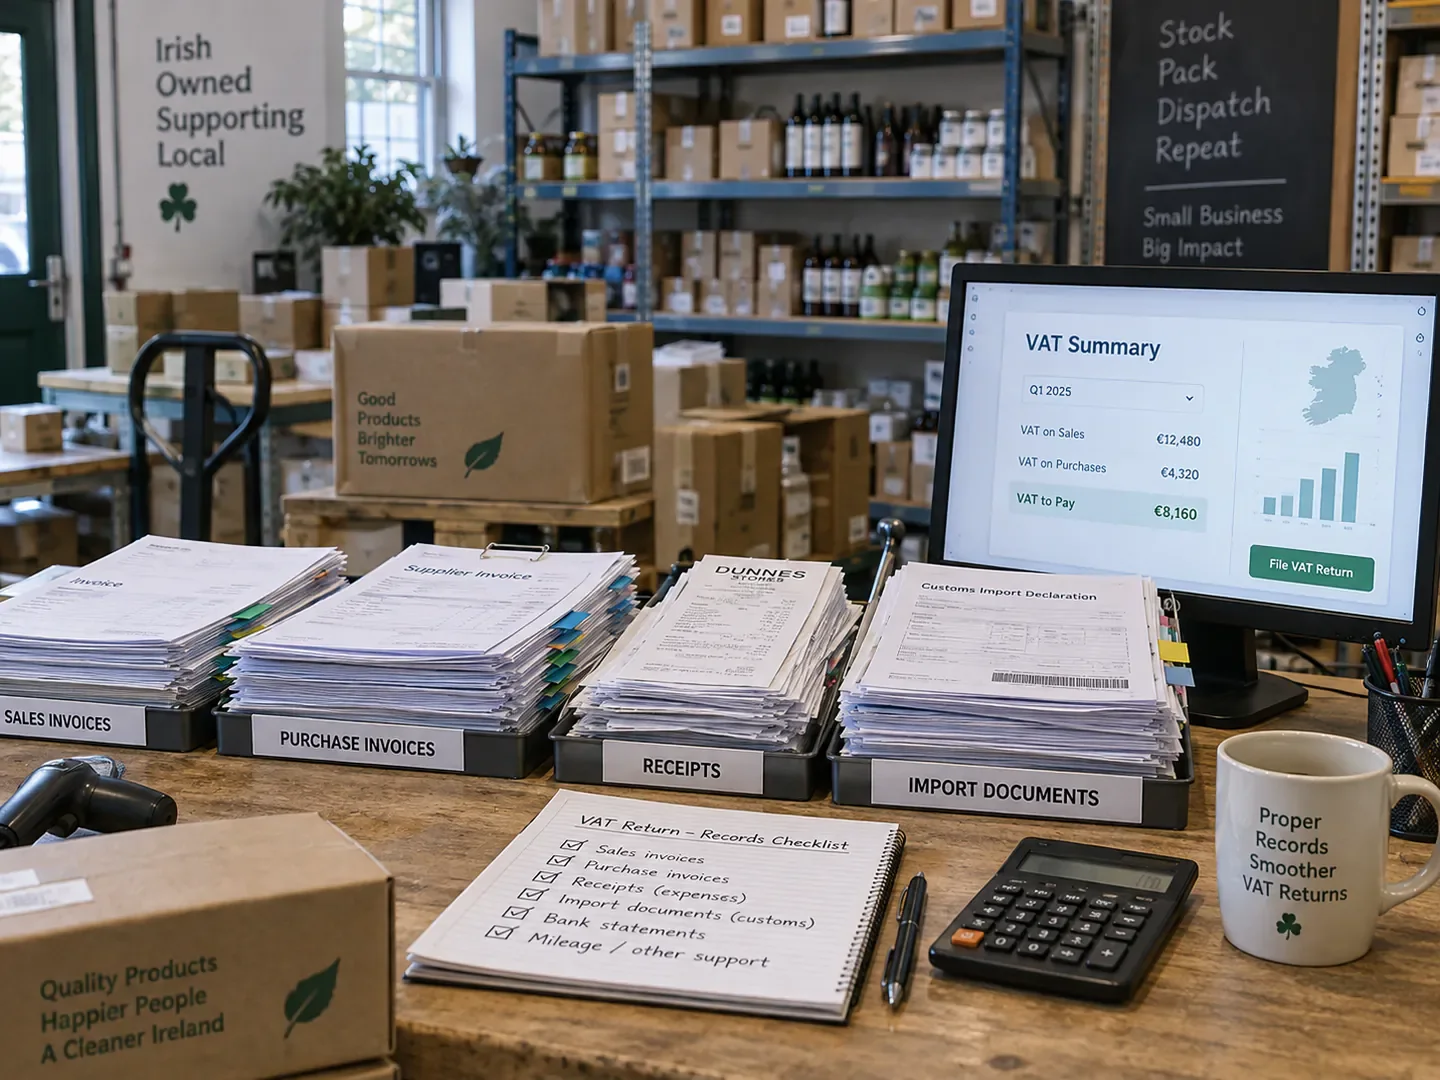
Keep sequential sales invoices and credit notes, with the correct dates, customer details and VAT treatment. Review unusual, exempt or cross-border sales separately.
- Sales invoices and credit notes
- VAT rates and tax points
- Evidence for zero-rated or reverse-charge transactions
Purchase evidence
Input VAT normally needs valid supporting evidence and must relate to the business. A bank transaction by itself may not be enough.
- Supplier invoices
- Import and customs documents
- Business-use review for mixed costs
Reconcile before submitting
Compare VAT control balances with the return, investigate duplicates and missing documents, and retain a clear calculation trail.
- Bank and supplier reconciliations
- VAT control account
- Filed return and payment confirmation